Gulf-to-Europe Railway to Ease Hormuz Disruption and land here. A Scenic sunset view of a metro train crossing Haliç Bridge in Istanbul with cityscape and water. by Zeynep Sude Emek via Pexels
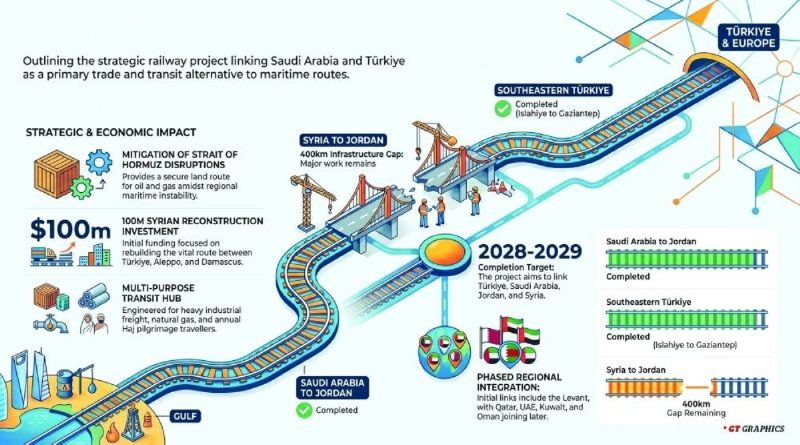
Turkiye and Saudi Arabia aim to build a railway to link the two countries with Jordan and Syria in the next three or four years, Turkish Transport Minister Abdulkadir Uraloglu said Sunday, adding other Gulf countries would also join the project.
Speaking to Al Jazeera, Uraloglu said the railway would help alleviate in future the problems that have arisen from the disruption of the Strait of Hormuz caused by the war in Iran. The project is described in a memorandum of understanding signed between Ankara and Riyadh last week on logistics cooperation and the railway sector.
In the initial phase, a rail link would allow for the transport of goods, oil, natural gas and people between Saudi Arabia, Turkiye, Jordan, Syria and Europe, Uraloglu said, adding that the Qatar, UAE, Kuwait, Oman, and possibly Yemen would be included later too.
“A train leaving from Saudi Arabia, from Riyadh already reaches several regions of Saudi Arabia. So this is a project for it to reach Turkiye via Jordan and Syria. We are talking about a route that will carry every type of freight via this route to Europe,” Uraloglu was cited as saying. He said the route from Saudi Arabia to Jordan’s border had been finished and on the Turkish side, the link was completed from Islahiye to Kilis and Gaziantep in southeastern Turkiye, near the border with Syria.
That leaves a gap of some 400km between Syria and Jordan, he said.
In addition to commercial trade, Uraloglu said the railway could also be used by people on the annual Haj pilgrimage.
Turkiye, which neighbours Syria, has built close ties with the government in Damascus after the fall of President Bashar al-Assad at the end of 2024 and has said it will help the country rebuild.
Uraloglu told Al Jazeera a financial plan would be drawn up for the rail project. The investment would include some $100mn to rebuild the route between Turkiye and Syria’s Aleppo, creating a direct link to Damascus.
In a recent study, scientists have proposed a blueprint to harness extremophytes—plants that thrive in multi-stress desert environments—for designing climate-resilient crops for arid lands and promoting sustainable agriculture practices.
The study, led by Mohsin Tanveer and WANG Lei from the Xinjiang Institute of Ecology and Geography (XIEG) of the Chinese Academy of Sciences (CAS), in collaboration with other researchers, was published in Global Change Biology on June 3.
Anthropogenic climate change is accelerating soil aridification and salinization, threatening over half of the global arable land and food security. Conventional crops are reaching their physiological limits under intensifying arid stress.
Josep Penuelas, research professor of the National Research Council of Spain, and co-corresponding author of the study, said: “Extremophytes do not merely survive harsh conditions; they actively regenerate ecosystem multifunctionality.”
WANG from the XIEG said: “Integrating extremophytes into diversified agroecosystems transforms non-arable land into productive, self-sustaining systems, and this is the essence of a circular bioeconomy for arid regions.”
The synergistic salinity-drought feedback loop and the niche for extremophyte resistance. (Image by XIEG)
For the study, researchers synthesized the functional traits of extremophytes to identify key transferable adaptation strategies. The team focused on two core mechanisms: the precise spatiotemporal orchestration of reactive oxygen species (ROS) as signaling molecules, and the active modification of the rhizosphere through targeted root exudation to recruit stress-protective microbiomes.
The study found that extremophytes avoid oxidative damage not by eliminating ROS, but by confining ROS signals to specific tissues and cellular compartments, allowing them to trigger tolerance responses without cellular toxicity.
Furthermore, these plants release specific exudates to enrich beneficial microbes such as Truepera and Halomonas. The enriched microbes help transform barren soil into a functional ecosystem and improve soil structure, water retention, and nutrient cycling. Domesticated crops have largely lost this sophisticated adaptive trait.
“The extremophyte rhizosphere is not just a zone of nutrient exchange; it is a highly orchestrated microbial recruitment engine,” said the XIEG’s Tanveer, also the first author of the study. He highlighted the critical role of microbiome-mediated adaptation: “By decoding how these plants signal and select their beneficial microbiome partners, we can engineer crops that actively build a protective living buffer around their roots.”
To develop a coherent framework for translating extremophyte biological mechanisms into sustainable agriculture practices, the research team proposes a circular bioeconomy model in which extremophytes such as Salicornia, Suaeda, and Alhagi are used for food, fodder, bioenergy, and phytoremediation on degraded lands. Intercropping extremophytes with cotton or spinach can reduce soil salinity by 40-51%, increasing yield and soil health.
“By restoring soil microbial networks and carbon sequestration pathways, these plants offer a nature-based solution that aligns directly with multiple UN Sustainable Development Goals, including Zero Hunger (SDG 2) and Climate Action (SDG 13),” Penuelas said.
System-level strategy of reactive oxygen species control as a survival strategy in an extremophytes in an arid environment. (Image by XIEG)
In sport, fairness matters. But when it comes to buying tickets to watch the world’s biggest ever sporting event, money matters too.
Attending the men’s Fifa World Cup 2026 will be much more expensive than any previous World Cup. And that’s not what fans were promised.
In fact, when the US, Canada and Mexico set out their original bid to host the tournament, they said a seat at the final would cost a maximum of US$1,550 (£1,174).
But by April 2026, the cheapest standard final ticket had reached US$5,785. The most expensive seats hit US$10,990 and later tripled. Just two days before the start of the tournament there were reports of 180,000 unsold tickets.
Politicians in New York and New Jersey have launched a formal investigation into allegations that Fifa has confused fans and inflated prices. Fans have complained of a lack of clarity, with many waiting hours in online queuing systems with no idea of the amount they’d have to pay when (and if) they were allocated tickets.
The increase in costs may remind some music fans of the 2024 scandal over Oasis concert tickets when customers watched prices more than double from £148 to £355 as they waited in online queues.
“Dynamic pricing”, when prices go up and down depending on levels of demand, will also be familiar to anyone who has been surprised by swift changes in the price of flights before a holiday. The same seat can cost more today than it did yesterday simply because more people want it.
Fifa denies that it is has engaged in dynamic pricing, saying that they use “variable pricing” instead. But from a consumer’s point of view, it amounts to the same result – the price of tickets that they want to buy changes, usually in an upward direction.
In response to the Oasis dynamic pricing episode, UK regulators later forced ticket sellers to commit to showing price ranges before fans join a queue. By using a “variable” system, Fifa positions itself outside that regulatory precedent entirely.
It faces no obligation to disclose prices in advance and no requirement to explain how they change.
A game of monopoly
But dynamic pricing isn’t always a bad thing for consumers. In fact, it can help them to get a better deal. Economists studying airline markets found that dynamic pricing can reduce prices as different airlines compete for passengers.
The trouble is that Fifa operates in a market with zero competition. No rival sells World Cup tickets. No substitute product exists.
The work of Nobel prize-winning economist Jean Tirole demonstrated that when a single firm controls an essential platform and operates at every level of the market, competitive discipline on pricing disappears. The operator stops seeking an efficient price and starts trying to extract the very maximum that the consumer will tolerate.
For football World Cups, Fifa sets the primary price. It runs the only sanctioned resale marketplace. It pockets 30% on every secondary transaction when unwanted tickets are sold on. It makes money on the first sale, and earns a bit more on the second.
No outcome costs Fifa money. No regulators intervene. But not everyone is prepared to pay out.
Adjusting for inflation, World Cup ticket prices have been stable for 30 years. Then Fifa introduced its new model and the entire pricing architecture shifted. This would explain all the unsold tickets.
For example, England’s semi-final and final allocations failed to sell out. Every fan who applied got a seat.
After the backlash, Fifa introduced a US$60 “Supporter Entry Tier” for every match, including the final. It amounts to roughly 10% of each national association’s allocation, a few hundred seats in stadiums holding up 80,000. As a pricing intervention, it changes nothing apart from an attempt to absorb criticism.
The day before the World Cub began Fifa president Gianni Infantino defended the level of ticket pricing, claiming that if they were cheaper the majority would have been resold on the black market. He added that the money generated was required to fund football development across the world.
Consumer research explains exactly what went wrong. When people buy a service rarely and can’t understand how the price was set, they don’t just feel frustrated, they feel cheated.
And when they feel cheated, they walk away. Fifa treated fan loyalty as guaranteed demand. Supporters’ reaction proved it isn’t.
Then, at the start of June, Fifa quietly slashed prices across all 104 matches and returned 70% of its block booked hotel rooms due to low demand – a last minute change of tactics probably designed to save face and avoid empty seats. But to many, desperately chasing lost fans after trying to extract more revenue than any World Cup in history already looks like foul play.
GlobalData’s Construction Projects Momentum Index for April 2026 shows the region in third place globally, with execution-stage activity recovering even as the Israel-Iran conflict weighs on the pipeline
The Middle East and North Africa’s construction project pipeline has demonstrated considerable resilience in the months since the military conflict between the US, Israel and Iran began in late February, although the regional performance has softened from its early-year highs and the full effects of the geopolitical shock continue to ripple through the project market.
GlobalData’s Construction Projects Momentum Index (CPMI) for the Mena region recorded 0.86 in April 2026, placing the region third globally behind North-east Asia and South Asia. The Mena score represents a 12% decline from 0.98 in March, which itself was unchanged from February. The regional three-month moving average eased modestly to 0.96 in April from 0.97 in March, suggesting that while momentum has nudged lower, the pipeline has not experienced the kind of sustained deterioration that might have been expected given the severity of the geopolitical disruption.
The resilience partly reflects the composition of the regional project market. The Mena region’s largest markets, the UAE and Saudi Arabia, have both continued to record solid momentum in the months following the start of hostilities in February. The UAE led the region in April with a CPMI of 1.20, easing only slightly from 1.30 in March, while Saudi Arabia recorded 0.94.
Mixed performance
The impact of the conflict is most visible at the country level, where a sharp divergence has opened up between markets directly exposed to the fighting and those insulated from it. Israel recorded the lowest CPMI score in the region in April at -3.26, reflecting substantial delays to major projects. The East Mediterranean Gas Pipeline was among the most significant casualties, with its Final Investment Decision pushed well beyond its original timeline. Iran, another direct participant in the conflict, registered a markedly weaker score of 0.53 in April, a stark reversal from its position as one of the region’s strongest performers in January, when it posted 1.31.
The conflict’s first major imprint on the index appeared in March, when the CPMI data reflected the initial shock of the escalation. Execution-stage momentum in the region dipped from 1.06 in February to 0.89 in March, while pre-execution activity slipped from 1.02 to 0.95. Infrastructure, which had been a strong performer earlier in the year, fell sharply to 0.53 in March from 1.06 in February, with the institutional sector also pulling back from 1.27 to 0.78. These moves are consistent with the channels through which conflict typically disrupts construction activity — cost inflation driven by energy price volatility, supply chain disruption and elevated risk premiums that delay investment decisions.
Stability signs
By April, some of these pressures had begun to ease, at least at the index level. Execution momentum recovered to 1.01, reversing the March dip, and infrastructure returned as the top-performing sector with a CPMI of 1.13. Commercial and leisure activity also remained solid at 0.94, building on gains that have been sustained throughout the conflict period.
Pre-execution momentum, however, continued to soften, falling to 0.86 in April from 0.95 in March. This is significant because the pre-execution stage — which captures project planning, design development and procurement preparation — is where investor caution and risk reassessment typically show up first. A sustained decline in this segment would signal a thinning of the future project pipeline, even if near-term execution activity holds up.
Kuwait offers a specific illustration of how supply chain and procurement disruptions linked to the conflict can affect individual markets. In January, Kuwait had recorded a CPMI of 0.27, depressed by delays to tender packages on Kuwait Oil Company developments including the SGC1, SGC II, SGC III and JLO Export Facility projects. The country recovered strongly to 1.43 in February and 0.90 in March, before falling back to 0.55 in April, with delays reported on Dorra Field developments. The oscillation reflects the vulnerability of projects with complex procurement requirements to the kind of supply chain uncertainty the conflict has generated.
Future pipeline
The Mena region entered 2026 from a position of strength, having ranked first globally in January with a CPMI of 1.05 — a 16% jump from December 2025’s 0.90. That momentum reflected broad-based gains across infrastructure, residential and institutional sectors, with Qatar, the UAE and Iran all posting scores above 1.20.
The conflict began when the region’s project pipeline was strong, and the data suggest that the buffer of accumulated momentum has helped absorb the initial shock. Whether that buffer holds through the remainder of 2026 will depend on how the conflict develops and, in particular, whether the more cautious behaviour visible in pre-execution activity translates into a deferral of new project launches. GlobalData’s data through April suggest the region is maintaining momentum, but the direction of the pre-execution trend is a forward-looking indicator to be watched in the coming months.
Workers at a construction site in Somalia. Photo: World Bank
.
STORY HIGHLIGHTS
South–South learning strengthened institutional capacity for managing environmental and social risks that are critical to enabling sustainable investment and job creation.
Practical lessons from Ghana highlighted the importance of legal clarity, coordination, and land governance in accelerating project delivery and investor confidence.
Strong environmental and social systems are essential enablers of infrastructure, private sector growth, and job creation, resilient development across Somalia.
.
When Somali officials arrived in Accra recently, they were not looking for new policies or templates. They wanted to understand how environmental and social (E&S) risk management works in practice, how institutions coordinate, and how E&S risks and impacts are managed as development projects move from planning to implementation.That practical curiosity sat at the heart of a South–South Knowledge Exchange and Learning Visit convened by the World Bank Group, bringing together regulatory institutions from Somalia and Ghana to share experience on strengthening environmental and social risk management in development.Delivered under the Somalia Programmatic Advisory Services and Analytics (ESSRM PASA), the exchange supports the World Bank Group’s efforts to strengthen institutions that are essential for sustainable investment, infrastructure delivery, and job creation.
Learning grounded in institutional practice
Rather than focusing on theory, the visit facilitated technical exchanges between institutions responsible for E&S protection, land administration, and key sectors such as extractives, transport, and energy. Participants engaged directly with their counterparts through institutional briefings, site visits, and facilitated peer-to-peer exchanges.
For fragile and transitioning countries, direct exposure to mature regulatory systems is critical, particularly for environmental and social risk management. Seeing how established institutions coordinate across government, sequence decisions, and manage risks in practice helps emerging systems scale faster.
Haroub Ahmed
World Bank Senior Environmental Specialist
With long-established regulatory institutions and extensive experience managing E&S risks across infrastructure, land, energy, and extractive sectors, Ghana provided a strong peer learning environment for the exchange. Its well-defined legal frameworks established environmental and sectoral regulators, and experience coordinating across institutions responsible for land, minerals, energy, and environmental protection offered participants concrete examples of how regulatory systems function in practice.
What stood out: clarity, coordination, and sequencing
Across discussions, participants highlighted the importance of clear legal mandates that can enable effective institutional oversight. Ghana’s regulatory framework is anchored in well‑defined laws that clarify roles, responsibilities, and decision‑making authority, reducing ambiguity and strengthening compliance.
Coordination emerged as another recurring theme. Inter‑agency collaboration in Ghana is formalized through legislation, board representation, and structured review processes, enabling environmental, land, and sector regulators to work together while maintaining distinct mandates.
Land administration was also a strong area of interest. Discussions highlighted how consolidated land management systems help reduce disputes, improve oversight, and build confidence among communities and investors, particularly infrastructure and extractives development.
Effective E&S systems as enablers of jobs and sustainable development
Throughout the exchange, a shared understanding became clear: environmental and social risk management is not simply a compliance requirement. Strong E&S systems are essential to advancing development priorities, including jobs, infrastructure, and private investment, while safeguarding people and the environment.
By improving regulatory clarity and coordination, effective E&S systems reduce uncertainty and delays that can discourage investment and slow project delivery. This is especially important as Somalia scales up investments in energy, transport, logistics, water, and productive sectors, central to the World Bank’s Jobs Agenda, Mission 300, and broader efforts to foster economic integration and growth.
Land and environmental governance also underpin the building of climate- resilience, smart development, and agri‑food value chains that support livelihoods. In fragile settings, clear and predictable institutions further contribute to state legitimacy and public trust, reinforcing stability over the long term.
Strengthening institutions for sustainable investment and jobs
The visit concluded with a debrief focused on translating learning into sequenced, capacity‑aligned actions. Participants identified priority areas to inform ongoing reforms, including establishment of the National Environmental Management Agency, strengthening environmental and social impact assessment systems, clarifying institutional mandates, and formalizing inter‑agency coordination, key building blocks for enabling sustainable investment and job creation.
Through the exchange, participants will take on follow‑up actions such as continued technical engagement, adaptation of legislative and regulatory materials, and development of a sequenced institutional roadmap aligned with capacity and available resources.
South–South exchange reaffirmed the value of peer‑to‑peer learning
“The Ghana exchange reinforced the value of South–South learning: countries engage as peers, lessons are practical and credible, and partnerships feel achievable,” said Grace Muhimpundu, World Bank Senior Social Development Specialist.
By grounding learning in lived institutional experience, the exchange reaffirmed the value of peer‑to‑peer learning in translating global good practice into context‑specific solutions. It also established a basis for follow-on work across legislation, ESIA systems, and institutional coordination, while opening channels for continued technical exchange, strengthening the systems needed for investment to drive private sector growth and create more and better jobs.
We use cookies on our website to give you the most relevant experience by remembering your preferences and repeat visits. By clicking “Accept”, you consent to the use of ALL the cookies.
This website uses cookies to improve your experience while you navigate through the website. Out of these cookies, the cookies that are categorized as necessary are stored on your browser as they are essential for the working of basic functionalities of the website. We also use third-party cookies that help us analyze and understand how you use this website. These cookies will be stored in your browser only with your consent. You also have the option to opt-out of these cookies. But opting out of some of these cookies may have an effect on your browsing experience.
Necessary cookies are absolutely essential for the website to function properly. This category only includes cookies that ensures basic functionalities and security features of the website. These cookies do not store any personal information.
Any cookies that may not be particularly necessary for the website to function and is used specifically to collect user personal data via analytics, ads, other embedded contents are termed as non-necessary cookies. It is mandatory to procure user consent prior to running these cookies on your website.